HGV Insurance.
Simplified.
From articulated trucks to logging jinkers, livestock carriers to tanker fleets — specialist cover for every vehicle over 3.5 tonnes. We connect operators with brokers who genuinely know this game. No hard sell, just straight-up honest advice.
Get a Specialist Quote
Specialist broker response within 24 hours
Insurance for Every Heavy Vehicle
Whether you run a single artic or a fleet of 50, we cover every vehicle class over 3.5 tonnes.
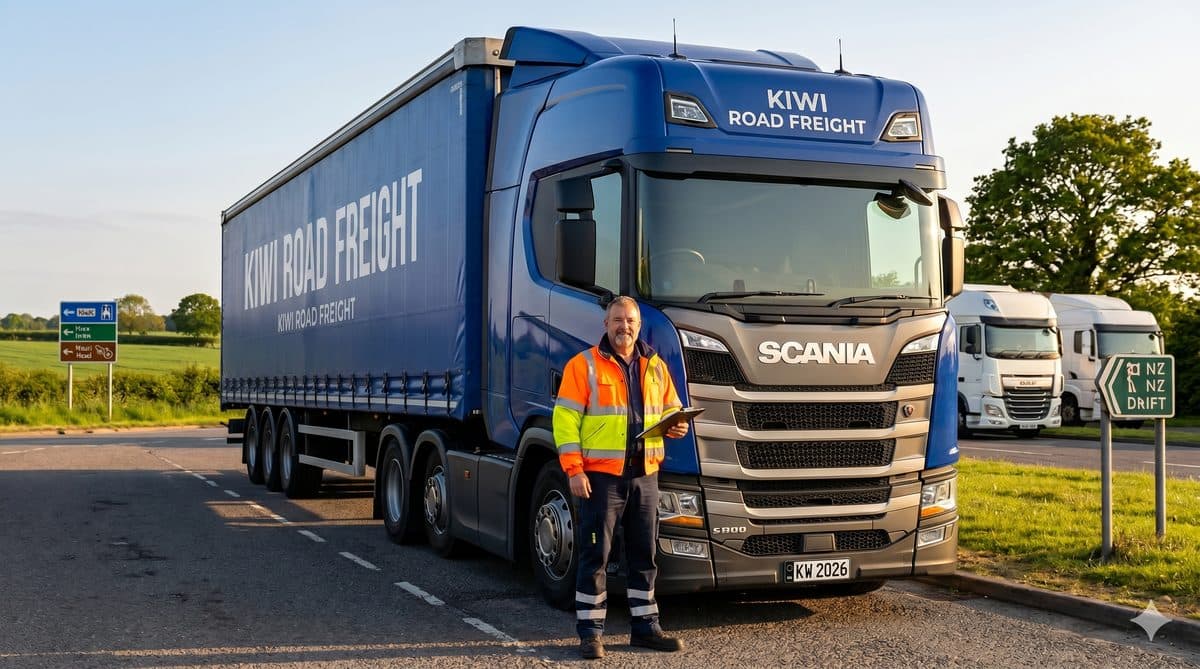
Articulated Trucks
Comprehensive cover for artic units, prime movers, and semi-trailer combinations carrying general freight across the country.
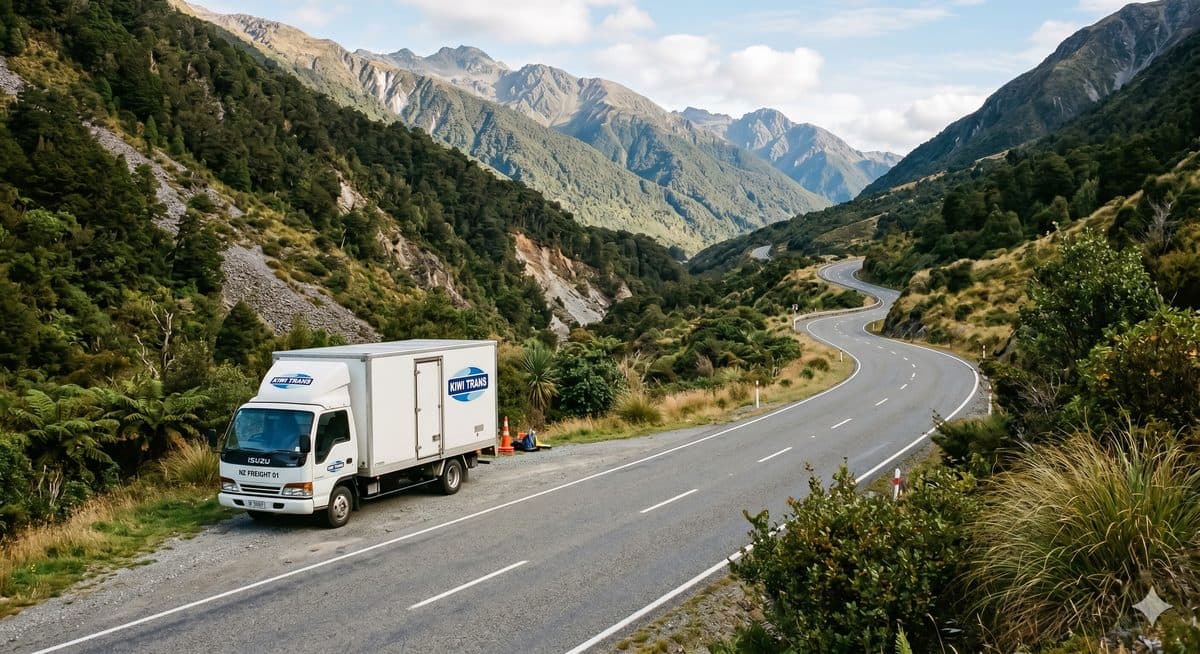
Rigid Trucks
Insurance for rigid body trucks, curtainsiders, flat decks, and crane trucks used for urban and regional delivery.
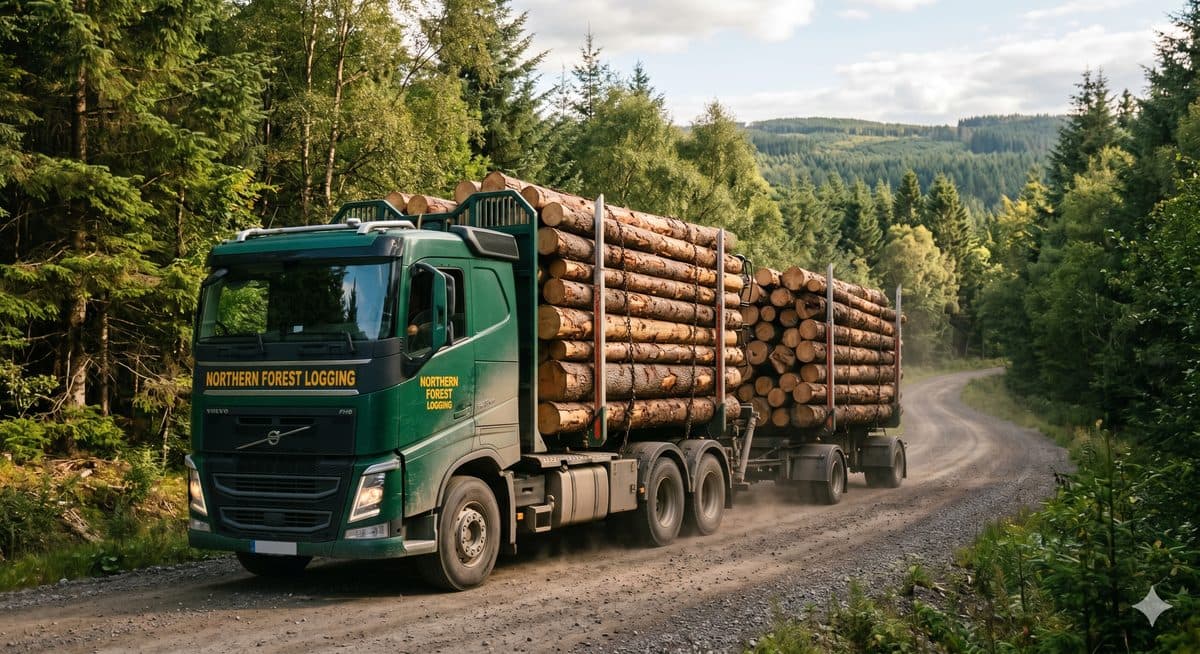
Logging Trucks
Specialist cover for logging trucks, timber jinkers, and forestry vehicles operating on bush roads and public highways.
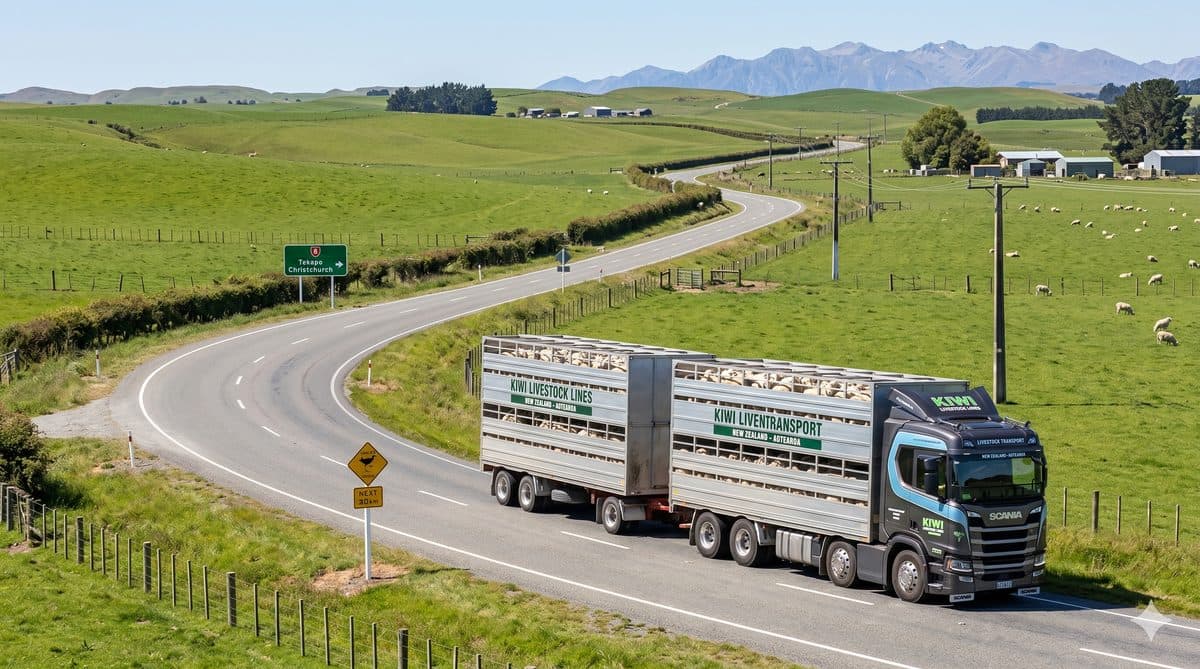
Livestock Carriers
Specialist insurance for livestock trucks, cattle trucks, sheep carriers, and horse floats operating on rural and state highways.
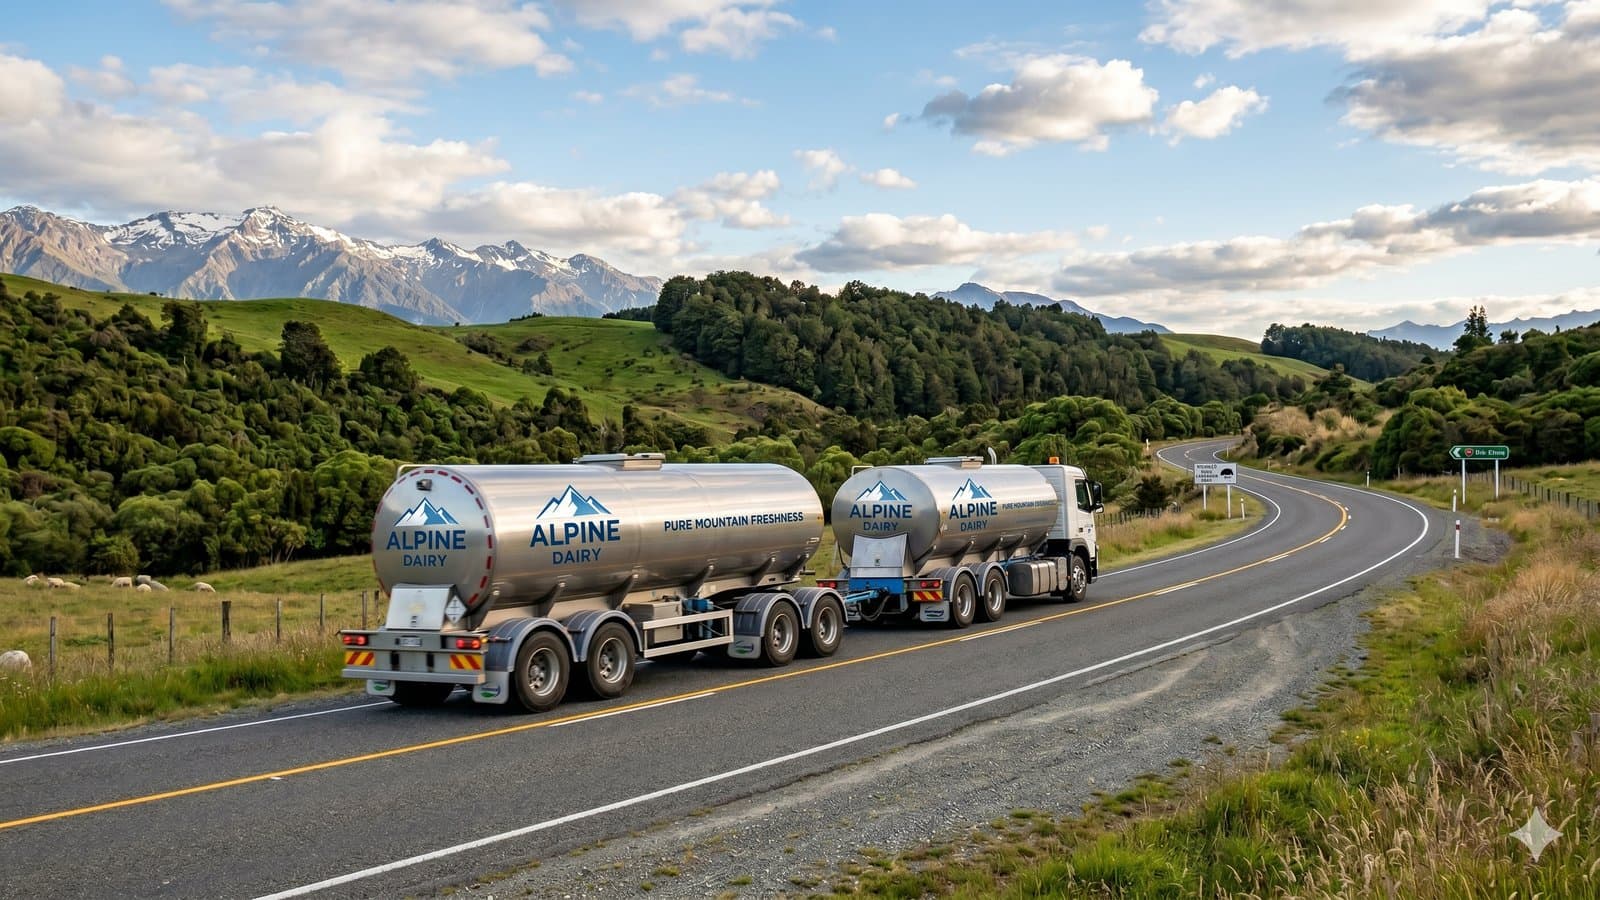
Tankers
Specialist cover for fuel tankers, milk tankers, water carriers, and chemical tankers with hazardous goods and environmental liability.
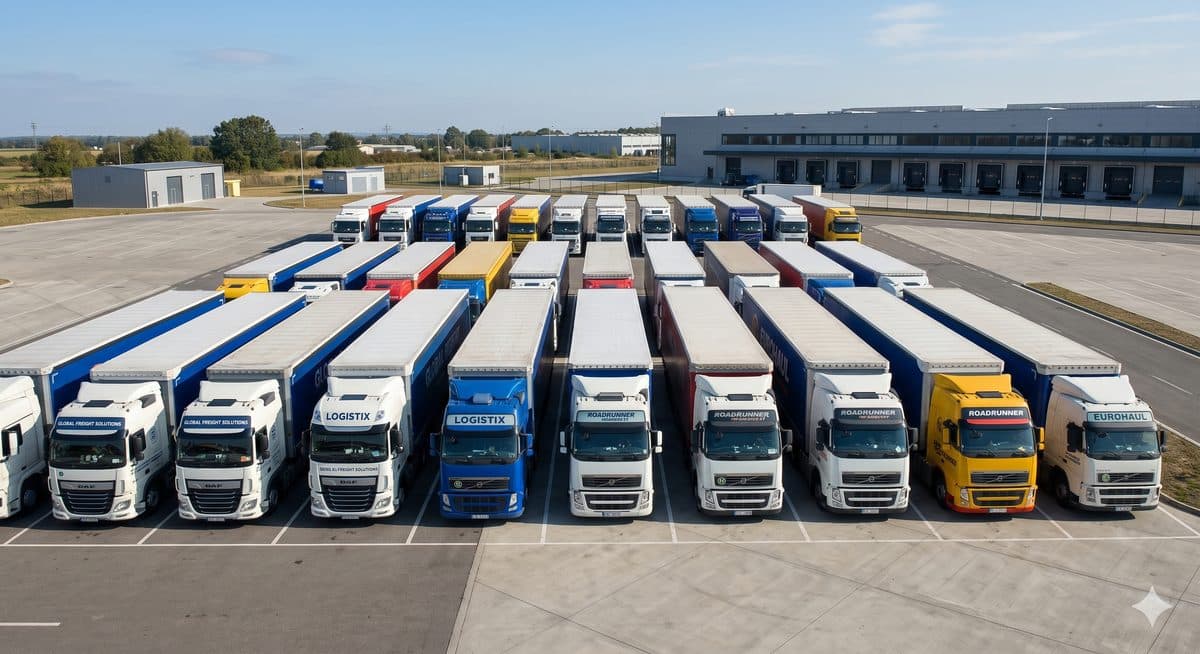
Refrigerated Trucks
Insurance for refrigerated trucks and controlled temperature vehicles carrying food, pharmaceuticals, and other temperature-sensitive cargo.
How It Works
Three steps to get specialist HGV cover — matched to your vehicle type, cargo, and routes.
Tell Us About Your Operation
Vehicle type, fleet size, cargo, routes, and current cover. Our form takes 2 minutes and covers everything your broker needs.
Matched to a Specialist Broker
We connect you with a broker who specialises in your vehicle type and sector — not a generalist who handles everything from cars to cargo ships.
Receive Your Quote
Your specialist broker contacts you within 24 hours with a tailored insurance programme structured for your specific operation.
No obligation · Specialist brokers only · Respond within 24 hours
The Covers That Make Up an HGV Policy
HGV insurance is more than just motor vehicle cover. Here are the covers that every operator should understand.
Comprehensive Cover
Agreed-value comprehensive cover for loss or damage to your HGV — whether from accident, fire, theft, storm, flood, or vandalism.
Learn more →Carriers Liability
Legal liability cover for goods in your care, custody, and control as a carrier — essential for any operator carrying freight belonging to others.
Learn more →Public Liability
Cover for your legal liability to third parties for bodily injury or property damage caused by your operations — beyond what your motor vehicle policy covers.
Learn more →Downtime Cover
Daily benefit payments while your HGV is off the road for covered repairs — keeping your cash flow intact when income stops.
Learn more →What a Truck Policy Does Not Cover
A motor policy covers the vehicle. It is not the whole of a transport operator's exposure, and the gaps show up at the worst possible moment. These are the covers that sit alongside it.
The freight on the deck
Your motor policy covers the truck, not the customer’s goods. Statutory limits under the Contract and Commercial Law Act apply unless you have contracted out of them — and many operators have, by signing a customer’s terms without reading the insurance clause.
A prosecution after a serious incident
Defending a prosecution is a separate cover from the damage to the vehicle. Note that Health and Safety at Work Act fines cannot be insured by anyone — sections 29 and 30 of that Act make such an indemnity of no effect. What can be covered is the cost of defending you.
Your yard, workshop and gear
Premises, hoists, tooling, parts stock and the office are not touched by a motor policy. Neither is a truck being worked on rather than driven, depending on how the wording treats it.
The revenue, not just the vehicle
Downtime cover on the motor policy replaces a vehicle or pays a daily amount. It does not answer a loss that stops the whole operation — a depot fire, a systems failure, or a key customer contract that cannot be serviced.
Claims from your own drivers
ACC covers personal injury in New Zealand, which makes employers liability here narrower than overseas. The useful question is what falls outside ACC rather than assuming nothing does.
A dispatch or telematics outage
Transport runs on scheduling, tracking and proof-of-delivery systems. An outage or a ransomware event stops the fleet earning without a single vehicle being damaged, and no motor policy responds to it.
Whether any of these matter for your operation depends on what you cart and how you run it, and that is a question for a broker rather than a website. Say what you do when you enquire and they will tell you which of these are worth discussing and which are not.
Running a Fleet?
Fleet insurance with burning cost rating, Fleet Risk Management Assessments, and single policy simplicity for operators running 3 or more HGVs.
Fleet Insurance →Specialist by Sector
Different sectors have different risks. We understand yours.
Freight & Logistics
General freight, 3PL, parcel delivery and long-haul transport on the national network.
Logging & Forestry
High-risk specialist cover for timber carriers, logging jinkers, and bush road operations.
Livestock & Agriculture
Animal mortality, carriers liability, and biosecurity cover for stock truck operators.
Construction
Tipper trucks, crane trucks, and civil works vehicles on construction sites nationwide.
Bulk Liquid & Tankers
Environmental liability, pollution cover, and specialist underwriting for fuel and chemical carriers.
Owner-Operators
Agreed value, income protection, and downtime cover for independent truck owner-operators.
HGV Insurance Resources
Plain-English guides for truck operators.
The Complete Guide to HGV Insurance in New Zealand
Everything truck operators need to know about insuring heavy goods vehicles — from articulated trucks to logging jinkers. A plain-English breakdown of covers, costs, and choices.
Agreed Value vs Market Value: Why It Matters for HGV Insurance
When your truck is written off, the difference between agreed value and market value can be $50,000 or more. Here's what every truck operator needs to understand before choosing their policy.
Logging Truck Insurance: What Forestry Operators Need to Know
Logging is the highest-risk sector in the heavy vehicle industry. Here's a specialist guide to the coverage that logging operators actually need — and the gaps that most find out about the hard way.
Frequently Asked Questions
What is a heavy goods vehicle (HGV) for insurance purposes?▾
Do I need separate insurance for my trailer as well as my prime mover?▾
How is HGV insurance different from standard vehicle insurance?▾
Can I insure my HGV online?▾
What is carriers liability and do I need it?▾
What is the difference between agreed value and market value?▾
Ready to Sort Your HGV Insurance?
Tell us about your operation and we'll connect you with a specialist who knows heavy vehicles inside out.
Get a Quote Today